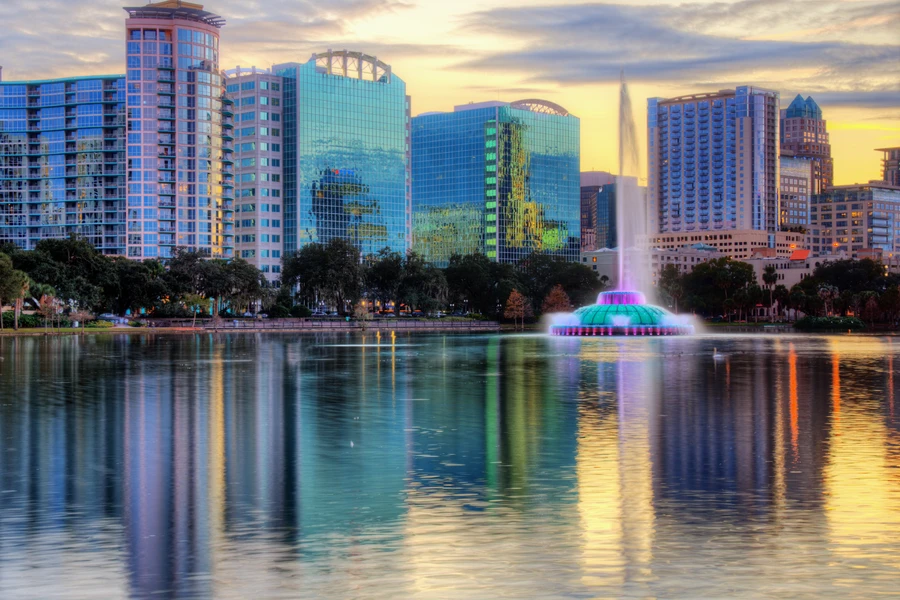
Orlando gets described as a tourist town, and it is one. It's also a place where people move to work at hospitals, universities, tech firms, and the airport, and where a lot of first-time buyers get their start. Financing a home here has its own rhythm. We're headquartered in Tampa, an easy drive down the interstate, and we lend across Florida and nationwide, so here's how the Orlando market looks from a lender's chair this year.
Inland Has Its Advantages
Orlando doesn't have a coastline, and that changes the insurance conversation. Coastal buyers spend the first week of every deal fighting for a wind policy. Orlando buyers still need homeowners insurance, and hurricanes still pass through, but carriers tend to price inland risk differently than they price the beach. Flood zones do exist here, mostly around the chain of lakes, so check the map before you fall in love. If you're comparing Central Florida against the coast, our guide to Florida's insurance market and your mortgage explains why the premium matters to the loan, not just the budget.
New Construction Runs the Show
Drive out to Horizon West, Winter Garden, Clermont, Lake Nona, St. Cloud, or Davenport and you'll see it: Orlando's growth is built new. Builders love to bundle incentives with their in-house or preferred lender, and the incentives are real. So is the fine print. The credit you get for using their lender is usually baked into the price somewhere, and you're allowed to use your own lender, even if the sales office implies otherwise. Get both quotes side by side, including the rate, the fees, and the closing timeline. A builder credit that comes with a slow closing and a rate you could beat elsewhere is not the gift it looks like.
HOA, CDD, and the Payment Nobody Quotes
Almost every newer Orlando community carries an HOA fee, and many carry a Community Development District assessment on top of it. A CDD is a bond the developer used to build the roads, ponds, and amenities, and you pay it back through your property tax bill. Underwriters count both in your monthly obligations, which means a house that looks affordable on a listing site can qualify for less than you expect once the fees are added. Ask for the HOA and CDD figures before you write an offer, and run them through our affordability calculator so the number you shop with is the number you can close on.
Hospitality Income and How Underwriters Read It
A big slice of Orlando works in hospitality, and hospitality pays in ways underwriting has to translate: tips, seasonal hours, overtime, second jobs, and app-based gigs. None of that disqualifies you. It does mean documentation matters. Underwriters want to see that variable income has a track record and isn't trending down, and they average it rather than taking your best month. If part of your income is on a 1099, read buying a home on 1099 income in Florida before you apply, because the way you file taxes changes what you qualify for.
Loan Programs That Fit Orlando
FHA is the workhorse for first-time buyers in the core neighborhoods. On the edges, in parts of Lake, Osceola, and Polk counties, USDA can put you in a home with no down payment if the address and your household income fit; our USDA income limits guide covers the details. Central Florida has a large veteran community, and VA loans do a lot of work here. Conventional makes sense for buyers with stronger credit and some savings. And if you're near the university, a small multi-unit with a tenant helping the payment is worth a look; we walked through that in our house hacking guide.
Buying in Orlando? Get a number that holds up.
We'll factor in HOA, CDD, insurance, and your real income so your pre-approval survives underwriting.
Rates and the Waiting Game
We don't predict rates, and you should be wary of anyone who does. What we can say is that waiting for a better rate in Orlando has its own cost. New inventory keeps coming, but the well-located resale homes still move, and insurance and fees don't wait either. Know what you can afford today, get a real pre-approval, and set a lock strategy with your loan officer once you're under contract. If rates improve later, refinancing is always on the table.
How to Win an Orlando Offer
Show up with a pre-approval from a lender who can close on the date you're promising, keep your inspection period realistic, and have your insurance quote in hand. On new construction, closing speed matters less because the builder sets the schedule. On resale, it matters a lot. A seller weighing two offers will often take the one that closes sooner and cleaner, and that's exactly what our process is built for. See how fast we move, and if you're relocating from out of state, our moving to Florida mortgage guide covers the timing.
Questions Florida Buyers Ask
Do I have to use the builder's lender to get the incentive in Orlando?
No. You can use any lender you choose. The builder may tie a specific credit to their preferred lender, so compare the full picture, rate, fees, and timeline, before deciding which deal is better.
What is a CDD fee and does it affect my mortgage approval?
A Community Development District fee repays the bond that built a community's infrastructure. It's collected on your tax bill, and underwriters count it in your monthly obligations, so it can lower how much you qualify for.
Can I get a USDA loan near Orlando?
Not in the city itself, but many outlying areas in Lake, Osceola, and Polk counties are USDA-eligible. Your household income has to fall under the area limit as well.
Orlando rewards buyers who understand the fees, the income rules, and the builder game before they start touring. If you want a pre-approval that accounts for all of it and a closing that beats the other offers, see how fast we move or give us a call.
Individual results may vary. Closing timelines depend on factors including appraisal, title, inspection, and borrower circumstances. 14 Days To Close does not guarantee a specific closing date.